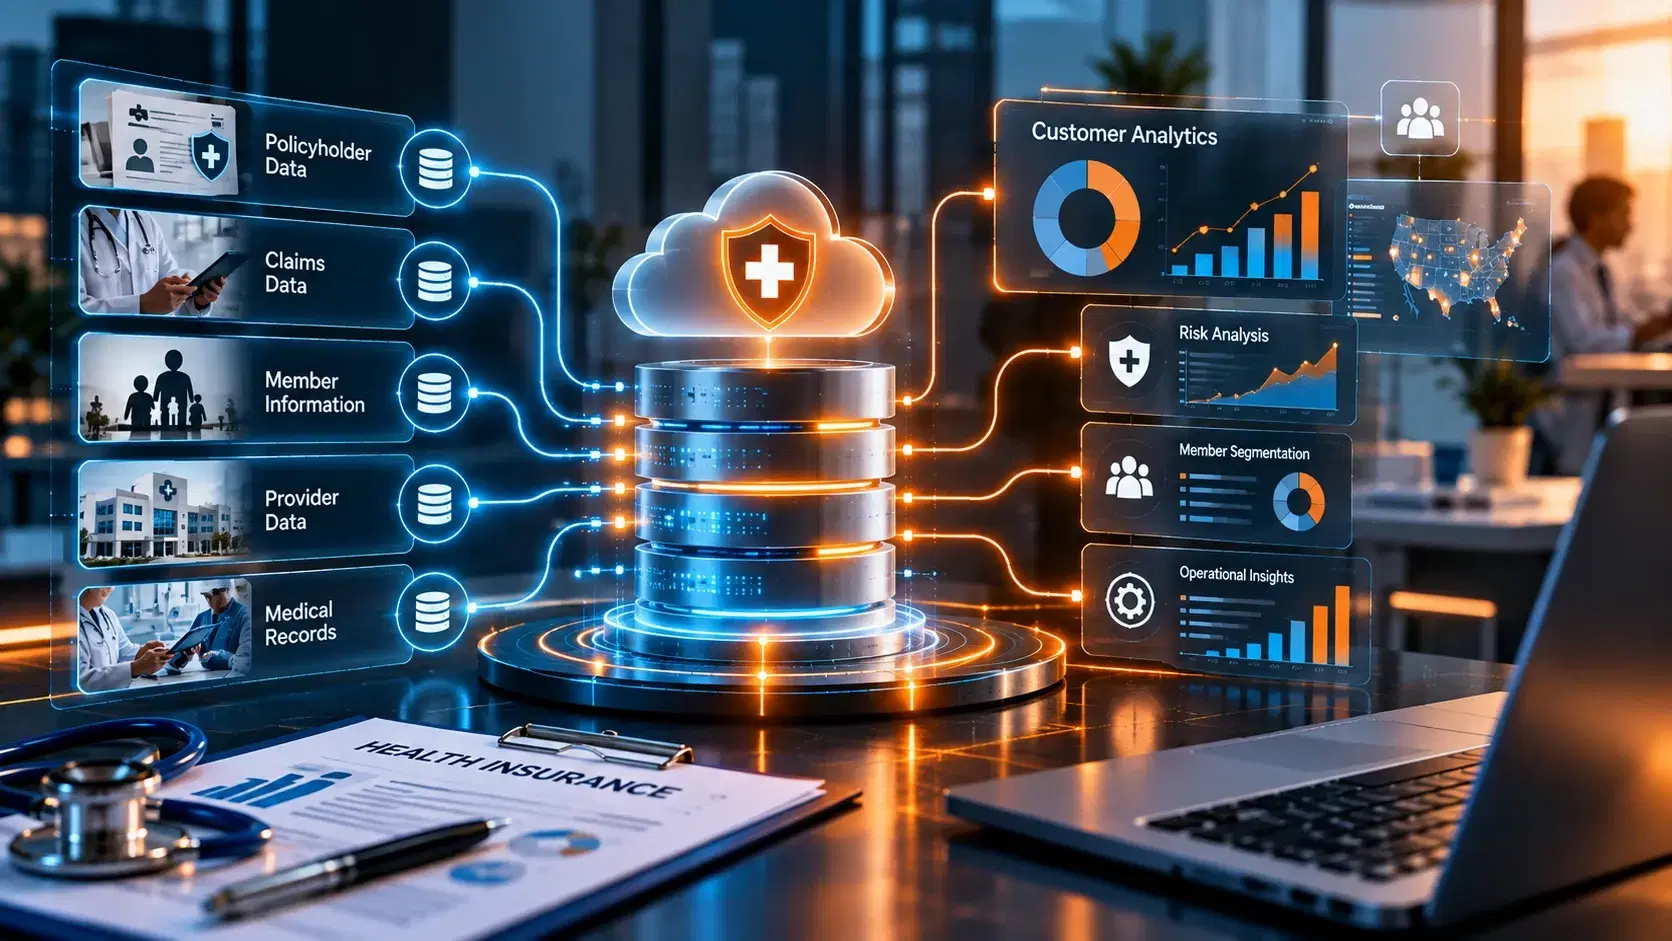

Small health insurance providers face many of the same data challenges as large insurers: claims arrive from different systems, eligibility information changes, regulatory reports must be accurate, and business teams want faster analytics. The difference is that smaller insurers usually have fewer people, tighter technology budgets, and less capacity to maintain a complicated data environment.
That changes what “good” health insurance data warehousing looks like.
A small insurer does not necessarily need the most feature-rich enterprise platform. It needs a data environment that can reliably integrate claims, support regulatory reporting, answer important business questions, protect sensitive information, and grow without requiring a large internal data engineering team.
What Data Warehousing Options Work Well for Small Health Insurance Providers?
For small health insurance providers, three practical options are worth evaluating: a managed cloud warehouse with a focused implementation partner, a customized warehouse built around existing technology, or a broader healthcare data platform when payer-specific capabilities justify the additional complexity.
Cloud platforms such as Snowflake, Microsoft Fabric, Databricks, and AWS can provide scalable infrastructure, but platform selection is only one part of the decision. Smaller insurers should give equal attention to implementation cost, claims data integration, maintenance effort, regulatory reporting needs, internal skills, and the amount of customization required.
In many cases, the best option is not the biggest platform. It is the simplest architecture that can reliably support today's requirements while leaving room for tomorrow's growth.
Start With the Work the Warehouse Must Actually Do
A common technology buying mistake is starting with vendor demonstrations.
For a smaller insurer, a better starting point is a short list of outcomes the warehouse must deliver. For example:
For a smaller insurer, a better starting point is a short list of outcomes the warehouse must deliver. For example:
- Can finance reconcile paid claims without combining multiple spreadsheets?
- Can operations analyze claim turnaround and denial trends without requesting a new extract from IT?
- Can regulatory teams reproduce previously submitted numbers?
- Can leadership understand enrollment, utilization, and cost trends from trusted information?
- Can the insurer add another data source without redesigning the entire environment?
These questions establish the minimum useful scope.
A warehouse that answers these questions consistently may create more business value than a much larger platform containing capabilities the organization does not currently have the staff or use cases to operate.
Option 1: A Managed Cloud Data Warehouse
A managed cloud warehouse is often a practical starting point for smaller insurers because much of the underlying infrastructure can be handled by the cloud service rather than an internal database administration team.
Snowflake, for example, provides a dedicated healthcare payer offering that includes Member 360, population health analytics, secure collaboration, and support for healthcare security and compliance requirements. (snowflake.com)
Microsoft Fabric takes a more integrated approach by combining data ingestion, engineering, warehousing, analytics, and Power BI capabilities within the Microsoft ecosystem. Its Data Warehouse supports enterprise relational warehousing, dimensional models, curated data marts, and governed semantic models. (microsoft.com)
These options can work particularly well when the insurer wants modern health insurance analytics without managing substantial infrastructure itself.
However, a managed platform does not eliminate implementation work. Claims logic, member relationships, data validation, reporting rules, access controls, and business definitions still need to be designed.
When This Option Makes Sense
Choose this path when the insurer wants a modern cloud foundation, has clearly defined analytics requirements, and can use either internal resources or an implementation partner to handle the insurance-specific data engineering.
Option 2: A Custom Warehouse Built Around Existing Technology
Sometimes a small insurer already has most of the technology it needs.
It may use Azure for applications, SQL databases for operational information, Power BI for reporting, and files or APIs for external claims information. Introducing an entirely separate enterprise data ecosystem may create more work rather than less.
In this situation, custom data warehousing services can focus on connecting and improving the existing environment.
The work might include creating reliable claims pipelines, building analytical models, establishing validation controls, organizing historical information, improving reporting performance, and creating reusable datasets for business users.
This is different from buying a packaged payer platform. The warehouse is designed around the insurer's actual systems and priority use cases.
When This Option Makes Sense
It is particularly useful when existing technology is fundamentally suitable but the insurer lacks internal data engineering capacity or needs specialized support to turn fragmented systems into a reliable analytical environment.
Option 3: A Lakehouse for Broader Data and Advanced Analytics
Some smaller insurers have requirements that extend beyond traditional dashboards and regulatory reporting.
They may want to process large historical datasets, combine structured and less-structured information, develop machine learning use cases, or eventually support advanced fraud and risk analytics.
A lakehouse platform such as Databricks may be worth considering in these situations.
Databricks combines data engineering, warehousing, data science, and machine learning around governed shared data.
Databricks combines data engineering, warehousing, data science, and machine learning around governed shared data.
But “more advanced” does not automatically mean “better.”
If the insurer's primary requirements are claims reporting, enrollment analytics, financial reconciliation, and a limited number of dashboards, implementing a broad lakehouse program may introduce capabilities that are not yet necessary.
When This Option Makes Sense
Consider a lakehouse when advanced analytics is part of a realistic roadmap rather than a future possibility with no defined business case.
Option 4: A Healthcare-Specific Data Solution
Another choice is adopting a solution designed specifically for health-plan data.

This can reduce some of the work required to interpret common healthcare domains because the solution already understands payer use cases.
Abacus Insights, for example, focuses specifically on health-plan data and provides capabilities for integrating and validating payer information for areas including risk adjustment, CMS interoperability, payment integrity, and other analytical use cases.
Healthcare-specific platforms can be attractive when domain functionality reduces implementation effort.
The tradeoff is flexibility. Smaller insurers should understand how easily the solution can accommodate unique internal processes, how data can be accessed outside the platform, and what happens if technology strategy changes later.
The tradeoff is flexibility. Smaller insurers should understand how easily the solution can accommodate unique internal processes, how data can be accessed outside the platform, and what happens if technology strategy changes later.
When This Option Makes Sense
Evaluate a healthcare-specific solution when payer-focused functionality is more important than having complete freedom over the underlying data architecture.
The Small-Insurer Test: Complexity per Business Outcome
For smaller insurers, one useful way to evaluate scalable data warehouse platforms is to measure complexity against the business outcomes they create.
Suppose two options can both produce trusted claims analytics. Option A requires three specialized engineers, multiple services, extensive custom orchestration, and ongoing platform administration. Option B requires a smaller managed environment and an implementation partner for periodic engineering support. Option A may technically provide more capabilities.
Option B may still be the better business decision. This leads to a useful evaluation principle:
Do not ask only, “Can this platform do what we need?” Ask, “What will it take us to operate what we need?”
That question is especially important for small health insurance providers.
Claims Integration Should Be Tested Before Platform Scale
Claims data integration is one of the best ways to test whether a proposed solution will work in practice. Instead of asking a vendor to demonstrate a generic healthcare dashboard, give the team a representative claims scenario. Ask how the solution will ingest the source, validate file or API delivery, process claim-level and service-line information, handle adjustments, retain history, reconcile financial amounts, and make the resulting data available for analytics. Then ask what happens when the source format changes. The answers reveal much more about long-term maintainability than a standard product demonstration.
Regulatory Reporting Needs Reproducibility, Not Just Performance
Smaller insurers may have fewer reporting resources, making manual regulatory processes particularly expensive in terms of staff time. A good warehouse should therefore help teams answer a simple but important question:
“Can we reproduce the number we reported?”
That requires more than storing the final result. Teams need controlled business logic, historical information, appropriate documentation, and a way to understand how reporting datasets were created.
CMS's data principles emphasize data quality, metadata, documentation, governance, privacy, security, and clearly assigned data ownership. These are useful principles for insurers building analytical and reporting environments of any size. (cms.gov)
For a smaller insurer, building these controls directly into pipelines can be more sustainable than relying on employees to remember manual reconciliation procedures.
What Does “Scalable” Mean for a Small Insurer?
Scalability does not necessarily mean designing today for hundreds of millions of members. For a smaller insurer, practical scalability might mean being able to:
- Add another claims source without rebuilding existing pipelines.
- Retain additional years of history without performance becoming unacceptable.
- Increase dashboard usage without disrupting ingestion.
- Add new employer groups, products, or lines of business.
- Introduce fraud analytics later without migrating everything again.
- Increase processing capacity without purchasing and maintaining new physical infrastructure.
A scalable data warehouse platform should therefore allow growth in manageable steps. Paying today for infrastructure designed around an unrealistic future scale can be just as problematic as choosing a system that cannot grow.
Customer Analytics Does Not Require Building Everything at Once
Smaller health insurers may also want better customer analytics, but the term can quickly expand into an enormous Member 360 program.
A more practical approach is to begin with the member questions that matter to the business. For example:
- Which members are currently eligible?
- How is utilization changing by plan?
- Which member populations are experiencing higher claim costs?
- Where are service or claims issues increasing?
- Which groups show meaningful changes in enrollment?
Once those questions can be answered reliably, additional member, service, engagement, or care information can be introduced as business requirements develop.
The warehouse grows with the analytical questions rather than attempting to model every possible customer interaction from the first release.
When Does a Data Warehousing Partner Matter More Than the Platform?
For small health insurance providers, this can be the most important purchasing question.
Platforms provide storage, processing, security features, orchestration capabilities, and analytical tools. They do not automatically understand how a particular insurer's claims should be reconciled or why two operational systems calculate a measure differently.
An implementation partner becomes particularly valuable when the insurer has a small internal data team and needs external support for architecture, integration, modeling, quality controls, deployment, documentation, and ongoing improvement.
Complere Infosystem can fit this type of requirement because its data engineering services work across cloud and analytics technologies rather than requiring insurers to adopt a proprietary warehouse product. For a smaller insurer, this allows the engagement to focus on the specific gaps preventing reliable analytics—such as claims integration, reporting datasets, quality controls, or warehouse modernization—while continuing to use appropriate existing technology.
The objective should be to reduce operational complexity, not create long-term dependency on the consulting partner. Documentation, maintainable pipelines, clear ownership, and knowledge transfer should therefore be included in the evaluation.
Use a “First 90 Days” Test When Comparing Partners
Rather than asking every potential partner for a three-year transformation roadmap, ask what useful result can realistically be delivered during the first 90 days.
A strong answer should identify a limited business problem, the required sources, measurable success criteria, major dependencies, and what business users will actually receive.
For example:
| Days | Activities |
|---|---|
| Days 1–30 | Understand claims sources, reporting requirements, existing architecture, data issues, and security constraints. |
| Days 31–60 | Implement a focused integration and analytical dataset for one priority area. |
| Days 61–90 | Validate results with business users, automate quality checks, document the solution, and move the agreed workload into regular use. |
The exact timeline will vary by organization and should not be treated as a guaranteed implementation schedule. Its value is as an evaluation tool: it forces vendors to explain how they move from architecture discussions to a usable business outcome.
Good health insurance data warehousing for a small insurer is not about choosing the smallest version of an enterprise architecture. It is about designing an environment appropriate to the insurer's claims volume, reporting obligations, internal skills, analytics priorities, and realistic growth.
A managed cloud warehouse can provide simplicity. A custom implementation can maximize the value of existing technology. A lakehouse can support broader engineering and advanced analytics. A healthcare-specific platform can reduce some payer-domain implementation work.
The right decision comes from balancing capability with operational effort. For smaller health insurers, the best solution is often the one that makes claims integration and regulatory reporting reliable today while allowing analytics to expand tomorrow without unnecessary complexity.
Build a right-sized health insurance data foundation that simplifies claims integration and reporting today while leaving room for analytics to grow.